Who Pays HOA Special Assessments on a Glendale Condo?
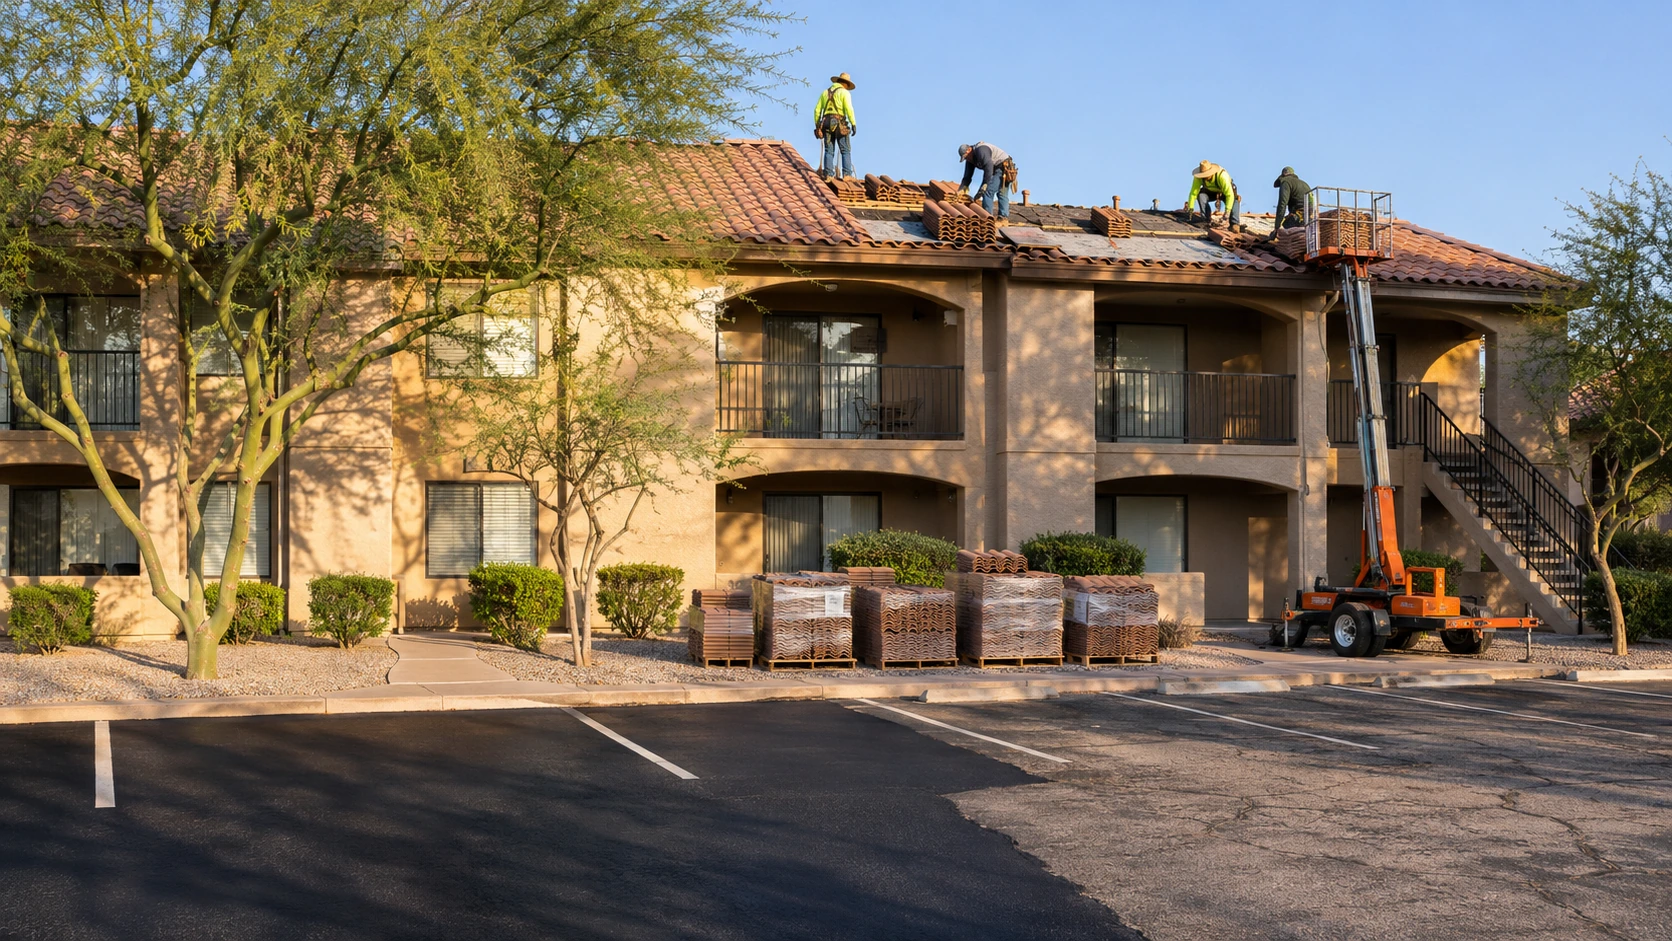
Who pays for HOA special assessments when buying a Glendale condo from out of state?
The seller typically pays any special assessments levied before closing, while the buyer assumes responsibility for assessments announced or levied after closing. But Arizona law allows negotiation of this responsibility during the purchase contract, making it essential to identify pending or planned assessments during your due diligence period before you’re financially committed.
Why Special Assessment Timing Creates Confusion for Out-of-State Buyers
When you’re buying a condo in Glendale from another state, the distance itself can make it harder to recognize warning signs that local buyers might catch. Special assessments are one-time charges the HOA levies to cover major repairs or improvements (roof replacements, parking lot resurfacing, structural repairs) that exceed the reserve fund. The confusion arises because assessments can exist in multiple stages: already paid, currently due, approved but not yet billed, or under consideration by the board.
This is usually where I slow buyers down, especially those coordinating remotely. The disclosure documents you receive during escrow may not reflect assessments that were discussed in board meetings but haven’t been formally approved yet. Arizona law requires sellers to disclose known special assessments, but if the HOA board is still in the planning phase, that information might not appear in your official paperwork. What matters most at this stage is not just reading the documents provided but understanding what questions to ask and when.
What Arizona Law Says About Special Assessment Responsibility
Arizona’s Planned Community Act and Condominium Act establish that the owner of record at the time an assessment is levied is generally responsible for paying it. If the HOA officially votes to approve a special assessment before your closing date, the seller is responsible. If the assessment is approved after you take ownership, you’re responsible. However, this default rule is negotiable during your purchase contract.
Most Arizona purchase contracts include language allowing buyers and sellers to allocate responsibility for special assessments differently than state law would otherwise dictate. This is where strategy matters. If you’re aware of a potential assessment during negotiations, you can request that the seller either pay it in full, credit you at closing, or reduce the purchase price to offset your future obligation.
What I watch for here is the gap between what’s legally required and what’s actually fair given the timeline. If an HOA has been discussing a major project for months but doesn’t formally vote until three days after your closing, you’re technically responsible under default rules, but that doesn’t mean you couldn’t have negotiated protection during the contract phase if you’d known to ask.
How to Identify Pending or Planned Assessments Before You’re Committed
The way to spot a pending special assessment on a Glendale condo is to read past the resale certificate and into the board’s meeting minutes and reserve study before your due diligence period ends. In Arizona, that window is your inspection period, which is 10 days by default under the standard Arizona REALTORS® (AAR) purchase contract.
The standard HOA documents you receive during escrow include the CC&Rs (the community’s recorded rules), bylaws, financial statements, meeting minutes, and a resale certificate. The resale certificate should disclose any current or approved special assessments, but it won’t necessarily flag projects the board is considering but hasn’t yet approved. This is where meeting minutes become critical, especially if you’re buying from out of state and can’t attend HOA meetings or speak casually with residents.
Reading through six to twelve months of board meeting minutes can reveal patterns: recurring mentions of deferred maintenance, engineering reports commissioned to assess major systems, or discussions about reserve fund shortfalls. These are indicators that a special assessment may be coming even if it hasn’t been voted on yet. If the minutes reference obtaining bids for roof replacement or discussing a loan to cover repair costs, that’s actionable information you can use during negotiations. Our guide to the HOA documents and rules to review before removing your inspection contingency walks through that package in more detail.
– Ashley Palomo
At this stage, I help clients narrow their focus to financial red flags in the HOA’s reserve study. Arizona law requires most HOAs to maintain a reserve study that projects the remaining useful life of major building components and estimates replacement costs. If the reserve study shows the roof has two years of useful life remaining and the reserve fund balance is inadequate to cover replacement, a special assessment is likely. When you’re managing this process remotely, having someone review these documents who understands both the legal requirements and the practical realities of Glendale’s condo market makes a measurable difference. If you’re weighing a community where costs are already climbing, our look at buying in a West Valley HOA community with rising fees and special assessments covers the bigger picture.
Negotiating Special Assessment Protection in Your Purchase Contract
When you find a potential or confirmed special assessment on a Glendale condo, you can ask the seller to pay it, ask for a credit at closing, or write protective language into your contract. Which one fits depends on whether the assessment has already been levied.
Once you’ve identified a potential or confirmed special assessment, you have several negotiation paths. The most direct approach is to request that the seller pay the assessment in full before closing. This works well when the assessment has already been levied and the payment schedule is clear. The second option is to request a credit at closing equal to the full assessment amount, which allows you to handle payment yourself after taking ownership.
The third option, often appropriate when an assessment is likely but not yet approved, is to build contingency language into your contract. This might specify that if an assessment exceeding a certain dollar threshold is approved between contract acceptance and closing, you have the right to renegotiate terms or terminate the contract without penalty. Arizona law allows significant flexibility here, but the language must be clear and specific to be enforceable.
This is where stress tends to show up if expectations aren’t clear from the beginning. Sellers may resist paying for assessments they don’t yet owe, and buyers purchasing from out of state may feel disadvantaged because they can’t easily verify the property’s condition or speak directly with HOA board members. What matters most is that your contract reflects what you’ve discovered during due diligence and protects you from absorbing costs the seller knew about or should have anticipated.
What Happens When Special Assessments Aren’t Disclosed
If you discover after closing that the seller failed to disclose a special assessment they knew about, Arizona law provides legal remedies. The Planned Community Act and Condominium Act both impose disclosure obligations on sellers, and failure to disclose known assessments can constitute fraud or breach of contract. However, proving what the seller knew and when they knew it can be complex, especially if the assessment was discussed informally at HOA meetings but not formally documented.
The more practical approach is to protect yourself during escrow rather than relying on legal recourse after the fact. This means requesting and reviewing all available HOA documentation, not just the standard resale package. If the HOA is unresponsive or slow to provide documents, that itself can be a red flag worth investigating further before you waive contingencies. For the other side of that package, our post on what Arizona’s HOA disclosure rules mean for sellers explains what a seller is expected to hand over.
What I watch for here is whether the seller or listing agent is actively facilitating document requests or creating delays. If you’re buying from out of state, you’re relying heavily on the responsiveness of people you may never meet in person, which makes having an advocate on the ground in Glendale essential.
Managing the Financial Impact of Special Assessments After Closing
If you close on a condo and later face an unexpected special assessment, your options depend on whether the assessment represents routine capital maintenance or an emergency repair. Routine assessments are typically payable over several months or even years, allowing you to budget accordingly. Emergency assessments for urgent repairs (burst pipes, structural damage, code violations) may require immediate payment or short payment windows.
Understanding Glendale’s condo market specifically matters here. Older condo complexes built in the 1980s and 1990s are more likely to face major system replacements in the near term, while newer developments may have healthier reserve funds and longer timelines before major assessments become necessary. If you’re comparing multiple properties, the age and maintenance history of the complex should factor into your decision, especially if you’re stretching your budget to qualify for the purchase.
Some HOAs allow owners to finance special assessments through the association itself or permit payment plans, but this varies by community. If the assessment is significant and your contract didn’t address it, you may need to tap savings, adjust your budget, or in severe cases, consider whether the financial obligation aligns with your long-term plans for the property.
Why Distance Increases Risk Without the Right Representation
Buying a condo from out of state eliminates some of the informal information-gathering that happens when you’re local. You can’t drive by the property multiple times, attend an HOA meeting, or speak casually with neighbors who might mention upcoming projects. The documents you receive become your primary source of information, and if those documents are incomplete or difficult to interpret, you’re making decisions with limited visibility.
This is usually where I step in to ensure nothing critical is overlooked. Arizona’s disclosure requirements are clear, but enforcement depends on buyers knowing what to request and when. If you’re coordinating remotely, having someone who understands Glendale’s condo inventory, knows which HOAs tend to be well-managed versus reactive, and can identify red flags in financial statements reduces the risk that you’ll be surprised by costs after closing. In Arizona, a title company handles escrow and closing, and our guide to how Arizona escrow and closing actually work covers that side of a remote purchase.
What truly matters is that you enter ownership with accurate expectations about your financial obligations. Special assessments aren’t inherently negative: they often indicate an HOA is maintaining the property responsibly rather than deferring necessary work. But they must be accounted for in your budget and negotiation strategy from the beginning.
Frequently Asked Questions About HOA Special Assessments on a Glendale Condo
How long does a seller have to disclose a special assessment in Arizona?
Sellers must disclose known special assessments in the resale certificate provided during escrow, typically within 10 days of the buyer’s request. Assessments approved before closing but not yet billed must still be disclosed.
Can I back out of a condo purchase if I discover a special assessment during escrow?
If you’re still within your due diligence period and haven’t waived contingencies, you can typically terminate the contract without penalty. After contingencies are removed, your options depend on the specific contract language.
Are special assessments tax-deductible for condo owners?
Special assessments for repairs and maintenance are generally not tax-deductible for primary residences, but assessments that add value or prolong the property’s life may be added to your cost basis, reducing capital gains tax when you sell.
How can I verify an HOA’s financial health before buying a Glendale condo?
Review the reserve study, monthly financial statements, and meeting minutes for the past year. Look for consistent reserve contributions, minimal accounts receivable, and proactive maintenance planning rather than reactive emergency spending.
What if the HOA approves a special assessment the day before my closing?
Under Arizona’s default rules, the seller would be responsible since they were the owner of record when the assessment was levied, but your purchase contract may specify different terms, so review your agreement carefully.
What is an HOA special assessment?
A special assessment is a one-time charge the HOA levies to cover major repairs or improvements, such as roof replacements, parking lot resurfacing or structural repairs, that exceed the reserve fund.
Who pays a special assessment approved after I close on a Glendale condo?
Under Arizona’s default rule, the owner of record when an assessment is levied pays it. An assessment approved after you take ownership is yours unless your purchase contract allocated it differently.
Can I negotiate who pays a special assessment?
Yes. You can ask the seller to pay it in full before closing, credit you at closing, or reduce the price, or add contract language that lets you renegotiate or terminate without penalty if a large assessment is approved before closing.
What Actually Matters When Buying From Out of State
The question of who pays special assessments matters because it directly affects how much capital you need to close and how quickly your budget stabilizes after moving in. The legal default (seller pays if levied before closing, buyer pays if levied after) provides a framework, but your protection comes from what you negotiate during the contract phase and what you uncover during due diligence.
When you’re coordinating a purchase from another state, distance should not increase your risk of unexpected costs. The documents exist, the disclosure requirements are clear, and the negotiation tools are available. What determines whether you enter ownership confidently or face immediate financial strain is whether someone with local knowledge is managing the details that don’t appear in standardized forms.
The goal is not to avoid special assessments entirely (that’s often unrealistic with older properties) but to ensure they’re factored into your decision-making process before you’re legally committed, not after you’ve already closed and moved in.
Reading the minutes, the reserve study and the contract before you’re committed is where I step in for buyers coordinating from another state, so you can make your move to Glendale with clarity and confidence.
If you want to talk through how special assessments could affect a Glendale condo you’re considering from out of state, let’s chat. You can reach me, Kasandra Chavez with the Chavez Dream Home Team, at 928-910-7401, or grab a time on my calendar.